
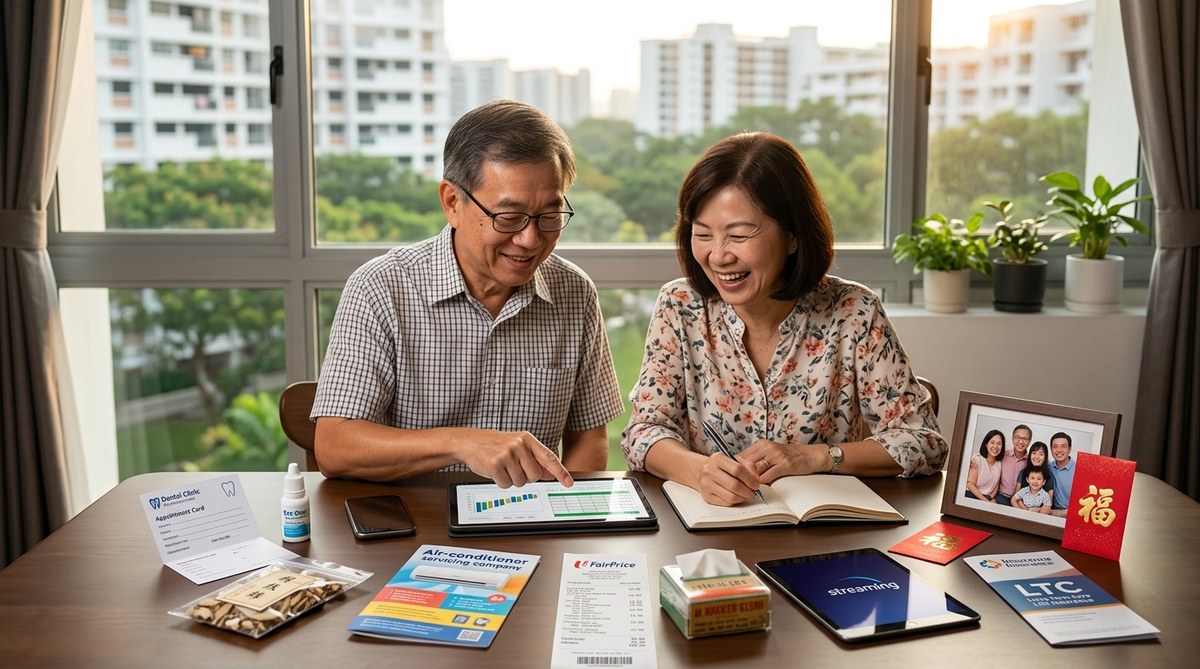
You have spent decades saving, investing, and planning for a comfortable retirement in Singapore. You know your CPF LIFE payouts. You have a rough budget for food, transport, and utilities. It all looks manageable on paper. But then the first few months of retirement arrive, and unexpected bills start piling up. A minor health procedure here, a major home repair there, and suddenly your carefully planned budget feels a little tight.
The truth is that many Singaporean retirees discover hidden costs only after they stop working. These expenses are rarely discussed in retirement planning guides. They can quietly drain your savings if you are not prepared. This guide will help you spot these hidden retirement expenses in Singapore before they become a problem.
Most Singaporean retirees underestimate their monthly spending by 20% to 30% because they forget costs like home maintenance, rising healthcare premiums, and helping adult children. A realistic retirement budget must include these hidden expenses. Planning for them now can protect your savings and give you peace of mind for decades to come.
The Hidden Costs That Surprise Most Retirees
When you plan your retirement budget, you probably think about the big items. Housing, food, transport, utilities. These are the obvious ones. But there is a whole category of expenses that many Singaporean pre-retirees overlook. These costs are not small. They can add hundreds or even thousands of dollars to your monthly spending.
Let us walk through the most common hidden retirement expenses in Singapore.
1. Healthcare Costs Beyond MediShield Life
MediShield Life provides basic coverage, but it does not cover everything. Many retirees discover this the hard way. A hospital stay for a minor surgery can leave you with a large bill if you only have basic coverage.
Here are the healthcare costs that often catch retirees off guard:
- Integrated Shield Plan premiums: These rise sharply as you age. A plan that costs $800 a year at age 50 can exceed $2,000 a year by age 65. And premiums tend to increase every year.
- Rider costs: Many retirees keep their full riders (which cover the first part of a hospital bill) without realizing how expensive they become. Some riders now cost over $1,000 annually.
- Outpatient treatments: Dental work, physiotherapy, and specialist consultations are not fully covered by basic plans. A single root canal can cost $500 or more.
- Health screening: Regular check ups become more important as you age. These are not free.
A good rule of thumb is to budget at least $300 to $500 per month for healthcare related expenses in retirement. This amount will vary depending on your health and the type of coverage you choose.
2. Home Maintenance and Renovation
Your flat or condo will not stay in perfect condition forever. Retirees often forget that their home needs regular upkeep. The costs can be substantial.
Consider these common expenses:
- Major repairs: Air conditioning servicing, plumbing fixes, and electrical work. A new aircon unit can cost $2,000 or more.
- Renovation: After 10 to 15 years, most HDB flats need some renovation. Kitchen cabinets, bathroom tiles, and flooring wear out.
- Condo maintenance fees: If you live in a private condo, maintenance fees can be $300 to $600 per month. These often increase over time.
- Painting and waterproofing: External repainting for HDB flats is subsidized, but internal painting is your responsibility.
Set aside a home maintenance fund. A good target is 1% of your property value per year. For a $400,000 flat, that means $4,000 annually or about $333 per month.
3. Helping Adult Children and Grandchildren
Many Singaporean retirees feel a strong sense of responsibility toward their children and grandchildren. This is a cultural norm, but it can become a major hidden expense.
Common ways retirees help their family:
- Wedding costs: Contributing to your child’s wedding can cost $10,000 to $50,000.
- Housing down payment: Helping your child buy their first HDB flat or condo.
- Grandchild expenses: Paying for tuition, enrichment classes, or childcare.
- Monthly allowances: Some retirees give their adult children monthly financial support.
This is a sensitive topic, but it is essential to be honest about it. If you plan to help your family, include these costs in your retirement budget. Otherwise, you may find yourself dipping into your savings more than you expected.
4. Rising Insurance Premiums
It is not just health insurance that gets more expensive. Other types of insurance also cost more as you age.
- Eldershield / CareShield Life premiums: These premiums increase over time. If you did not opt out, you will need to pay them.
- Travel insurance: If you plan to travel in retirement, travel insurance becomes more expensive for older travelers.
- Life insurance: Term life insurance premiums rise significantly after age 60.
Review your insurance policies every two years. You may be able to reduce coverage or switch to a more affordable plan.
5. Inflation on Everyday Items
Inflation is a hidden expense that affects everything. The $5 plate of chicken rice you enjoy today may cost $7 in ten years. Your monthly grocery bill will creep up year after year.
Retirees often forget to factor inflation into their long term budget. A retirement plan that works today may fall short in 10 or 15 years.
Use this table to see how inflation affects your spending over time:
| Expense Category | Current Monthly Cost | Cost in 10 Years (3% inflation) | Cost in 20 Years (3% inflation) |
|---|---|---|---|
| Groceries | $400 | $538 | $723 |
| Utilities | $150 | $202 | $271 |
| Transport | $100 | $134 | $181 |
| Healthcare | $300 | $403 | $542 |
| Dining out | $200 | $269 | $361 |
These numbers show why it is important to plan for rising costs. A budget that feels comfortable today may not feel comfortable a decade from now.
6. Transport and Mobility Costs
Many retirees assume their transport costs will drop after they stop commuting to work. That is not always true.
- Public transport: You may travel more for leisure, visiting friends, or running errands.
- Private transport: If you own a car, costs like COE renewal, road tax, insurance, and maintenance will continue.
- Grab and taxis: As you age, you may rely more on ride hailing services for convenience.
- CPF top ups for travel: If you travel frequently, your transport costs can be significant.
A practical step is to track your actual transport spending for three months after retirement. Use that number as your baseline.
7. Gifts, Celebrations, and Social Obligations
Retirement often means more time for social activities. Weddings, birthdays, Chinese New Year, and other celebrations come with costs.
- Ang pows: During Chinese New Year, you may give ang pows to children, grandchildren, and relatives.
- Gifts: Birthday and anniversary gifts for family and friends.
- Dining out: Meeting friends for meals can become a regular expense.
- Hobbies and classes: Many retirees take up new hobbies like photography, cooking classes, or fitness programs.
These costs are easy to overlook because they feel optional. But they are part of a fulfilling retirement. Budget for them.
A Step-by-Step Process to Find Your Hidden Expenses
You do not need to guess what your hidden costs will be. Here is a practical process to identify them.
-
Track your current spending for three months. Use a budgeting app or a simple spreadsheet. Categorize every expense. This will show you where your money actually goes.
-
Identify one time costs. Think about upcoming expenses like a home renovation, a wedding, or a major health procedure. Add them to your retirement plan.
-
Check your insurance policies. Review your Integrated Shield Plan, CareShield Life, and other policies. Note the premiums for the next five years. Expect them to rise.
-
Talk to your family. Have an open conversation with your children about financial expectations. Know whether they expect your help with big life events.
-
Add an inflation buffer. Increase your projected expenses by 3% each year. This will give you a more realistic picture of your future needs.
-
Review your plan annually. Your retirement budget is not a set and forget document. Review it every year and adjust as needed.
Common Mistakes Singaporean Retirees Make
Even with good intentions, retirees often fall into these traps.
- Underestimating healthcare costs: They assume MediShield Life is enough. It is not for many situations.
- Ignoring home maintenance: They forget that their flat will need repairs.
- Overestimating CPF LIFE payouts: CPF LIFE is a great foundation, but it may not cover all expenses.
- Not planning for inflation: They use today’s prices to plan for tomorrow’s spending.
- Helping children without a limit: They give generously without considering their own long term needs.
“The biggest mistake I see retirees make is assuming their expenses will drop after they stop working. In reality, many retirees spend more in the first few years of retirement because they have more time for social activities, travel, and hobbies. Plan for an active retirement, not a frugal one.” – David Tan, Certified Financial Planner
How to Build a Realistic Retirement Budget
A good retirement budget is not just about covering your basics. It is about living the life you want without financial stress.
Here is a simple framework:
- Fixed costs: Housing, utilities, insurance, transport. These are your non negotiables.
- Variable costs: Food, dining out, hobbies, gifts. These can be adjusted.
- One time costs: Home repairs, weddings, health procedures. Plan for these separately.
- Emergency fund: Keep 6 to 12 months of expenses in a high interest savings account for unexpected events.
For a detailed look at how much you really need, read our guide on how much money you need to retire comfortably in Singapore.
Planning for a Secure and Enjoyable Retirement
Retirement should be a time of freedom, not financial worry. By identifying these hidden retirement expenses in Singapore now, you can build a budget that truly covers your needs.
Take the time to review your current spending, talk to your family, and adjust your plan for inflation. These small steps will protect your savings and give you confidence in your financial future.
You have worked hard to reach this stage. You deserve a retirement that is comfortable, enjoyable, and free from unpleasant surprises. Start planning for the hidden costs today, and you will thank yourself later.